Richmond, Virginia’s real estate market has changed dramatically over the past century, moving from post-Civil War construction to today’s technology-driven industry. At the center of th...
Madison, New Jersey Has Run Out of Homes to Sell

Written by:
Date:
14 Sep 2026
Share via Facebook

Share via Linkedin

Share via X

Copy to clipboard

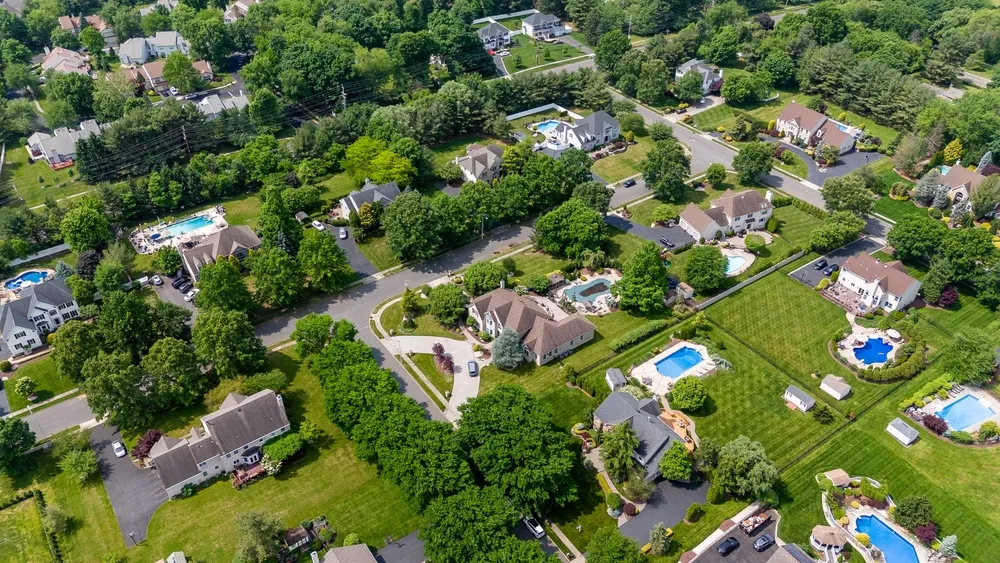
Madison, New Jersey has an average home sale price of $1.6 million over the past six months – up 19 percent year over year, according to Marybeth Eckhardt, a partner at Boyd Eckhardt Partners. There are currently nine homes listed for sale in the borough, two of which are already in attorney review. That leaves seven available properties in a town of roughly 15,000 people, serving a buyer pool that draws steadily from Hoboken, Jersey City, Brooklyn, and Manhattan. The math is straightforward: there are far more buyers than homes. What is less obvious is that even in a market this tight, sellers who misread pricing or skip preparation leave money on the table.
Eckhardt has worked the Madison and surrounding Morris County market since 2006. She says the current environment rewards a specific approach to listing – one that runs counter to sellers’ instincts about what a hot market allows them to do.
Why Pricing Below Comps Has Become the Default Strategy
A decade ago in this market, the standard approach was to price high and negotiate down. That model has inverted. Eckhardt says the strategy now is to price below recent comparable sales and let buyer competition push the final number higher.
“If a seller is looking to get $1.6 million for the house, we would price under that – somewhere probably between 1.4 and 1.5 to get that 1.6,” she says.
The logic depends on the depth of the buyer pool. Madison, Chatham, and Morristown are commuter towns along New Jersey Transit’s Midtown Direct line into Midtown Manhattan. The typical buyer profile has stayed consistent for two decades: married couples with one or two children, relocating from urban apartments, looking for strong schools and walkable downtowns. The difference now, according to Eckhardt, is that many commute only three or four days a week rather than five, but proximity to the train still drives location premiums.
When a house is staged, priced correctly, and in a strong location, Eckhardt says it typically sells in a weekend. The average days on market over the past six months is 23, but that figure includes a five-to-seven-day “coming soon” period and New Jersey’s attorney review process, which adds another three to seven days. The actual marketing window for a well-positioned listing is narrow.
Buyer Selectivity in a Market With Almost Nothing to Buy
Despite the scarcity, buyers are not writing offers on everything. Eckhardt describes them as more selective rather than less motivated – a distinction that matters for how sellers prepare.
Properties that lack strong location, proper staging, or accurate pricing sit longer. Seller concessions, however, remain essentially nonexistent. The inventory shortage keeps the market firmly in sellers’ favor, but only for sellers who do the preparation work. As Eckhardt puts it, “A quick sale doesn’t always mean an easy sale.”
On the buyer side, the competition is wearing. Eckhardt says she has had clients lose out on five, ten, or fifteen houses before finally getting one under contract. The recurring question from those buyers is whether they are overpaying. Her response is practical: if you plan to be in the house for a long time, you have to pay what you need to pay to get it.
The Lock-In Effect Holding Inventory Down
The inventory constraint is not just a function of demand. Eckhardt points to a pattern among existing homeowners: sellers who have lived in their homes for decades want to downsize, but there is nothing for them to buy, so they don’t list. “You’re not seeing the turnover that we saw a number of years ago,” she says. This pattern has persisted with little change since roughly the start of COVID, according to Eckhardt – about five or six years.
Without a meaningful increase in listings, prices have continued to climb. That pressure extends to land values, which have changed the economics for builders. Eckhardt estimates that a half-acre lot in Madison was worth roughly $800,000 ten years ago, with builders knocking down the existing structure and selling a new home for $2.2 to $2.3 million. Today, that same half-acre is worth approximately $1.4 to $1.5 million – but the finished product sells for $3.5 to $4.5 million. Land costs have nearly doubled, but builders continue developing because end-sale prices have risen proportionally.
For investors looking at the area, the entry point has moved substantially. Properties that once served as affordable renovation or teardown opportunities are now priced at levels that make the investment math harder. “It’s really difficult for an investor in this area right now,” Eckhardt says. “You can still find deals, but they’re more difficult to find than they were a few years ago.”
What to Watch Over the Next Year
Eckhardt says the variable she monitors most closely is whether inventory levels shift – watching how quickly new listings appear, how many offers come in, and the list-to-sale price ratio. So far, nothing has broken the fundamental pattern. “As long as inventory remains low, we will continue to see that trend,” she says. “Low inventory will continue with the rising prices.”
For sellers weighing whether to list now or wait, Eckhardt says the answer depends on the same question it always has: whether there is somewhere else to go. Until more existing homeowners find a next home to move into, the lock-in cycle will keep supply constrained – and the pricing strategy that works best will remain the counterintuitive one: list low, and let the buyer pool do the rest.
About the Expert: Marybeth Eckhardt is a partner at Boyd Eckhardt Partners, and has worked the Madison and surrounding Morris County, New Jersey market since 2006.
This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.
Similar Articles
Explore similar articles from Our Team of Experts.